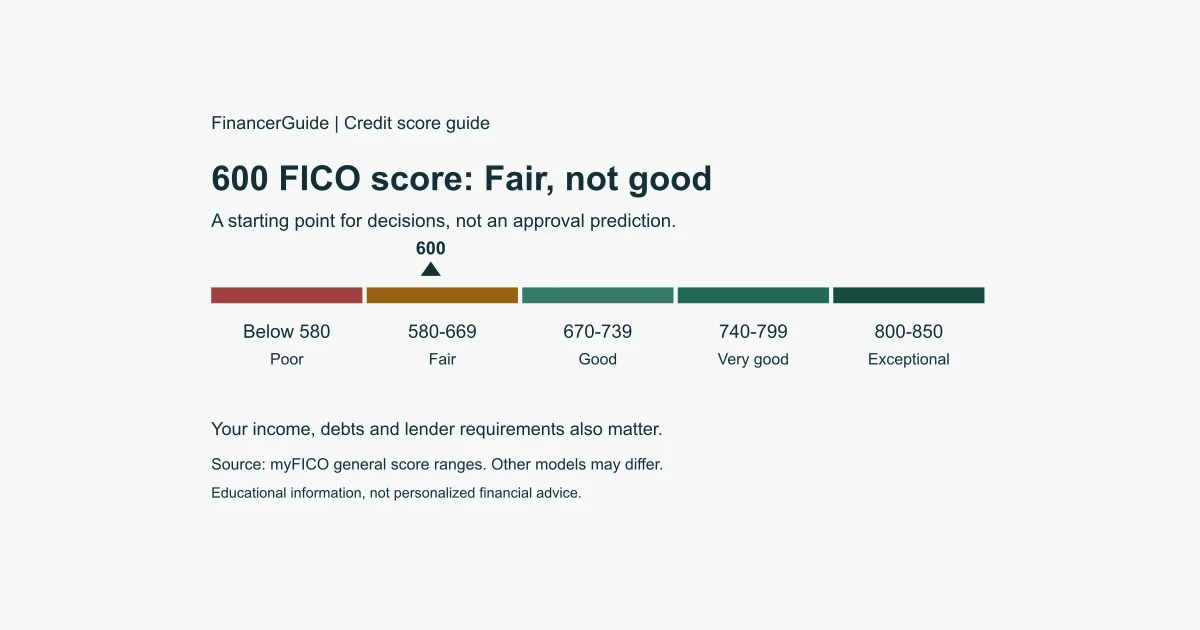
Is 600 a bad credit score? A 600 FICO score is fair, not good: it falls in FICO's 580-669 fair range. Other scoring models can label the same number differently, and lenders may offer fewer choices or more expensive terms at this level. It does not automatically mean you will be denied credit.
Your next step is to check which score you are viewing, review your credit reports, and work out an affordable payment before applying. Income, existing debts, the product you want, and the lender's requirements all matter alongside the score.
This guide is for US readers and is educational information, not personalized financial advice. Examples are illustrations, not lender offers or approval predictions.
Is a 600 Credit Score Bad?
FICO's credit score guide places 600 in its fair range. Calling it simply "bad" misses an important distinction: it is below the good range, but it is not in FICO's lowest category.
| General FICO score range | FICO category |
|---|---|
| Below 580 | Poor |
| 580-669 | Fair: this includes 600 |
| 670-739 | Good |
| 740-799 | Very good |
| 800-850 | Exceptional |
These are FICO's general categories, not universal lending cutoffs. A lender may use a different model, version, or credit bureau than the score shown in your banking app. Our FICO vs. VantageScore guide explains why two scores can differ.
Two people with a 600 score may also have different credit histories. One might have recent missed payments; another might have high card balances. Read the factors supplied with your score rather than assuming the number tells the whole story.
What Can You Get With a 600 Credit Score?
The useful question is not only whether you can qualify, but whether the offer is affordable. Use this checklist before submitting an application.
| Product | What may be possible | What to check first |
|---|---|---|
| Personal loan | Some lenders may consider your application | APR, fees, income requirements, and net proceeds |
| Auto loan | Financing may be available, potentially at a higher cost | Vehicle price, down payment, term, and total repayment |
| Mortgage | Some programs may consider borrowers at this score | Program rules, lender requirements, DTI, and cash needed |
| Credit card | A secured card or some other cards may be options | Deposit, annual fee, APR, and credit bureau reporting |
Personal Loans
You may be considered for a personal loan with a 600 credit score, but there is no universal qualifying minimum across lenders. An unsecured lender has no pledged asset to recover if you fail to repay, so income, payment history, and existing obligations matter.
Compare the amount you actually receive after any origination fee, not just the face value of the loan. Ask whether checking an offer uses a soft credit inquiry and whether a full application will trigger a hard inquiry. Prequalification is not final approval.
For a secured loan, identify the asset at risk. Using a vehicle or savings as collateral does not turn an unaffordable payment into a safe one. Avoid offers that promise guaranteed approval or demand an upfront payment to guarantee a loan; the FTC explains advance-fee loan warning signs.
Auto Loans
A 600 credit score does not automatically rule out an auto loan. The car's value and age, your down payment, income, debts, and the lender's policies can all affect the decision.
Compare financing before choosing a vehicle. A longer term can lower the monthly payment while increasing total interest and the risk of owing more than the car is worth. Include insurance, registration, maintenance, and fuel in your budget, not just the loan payment.
Mortgages
Buying a home may be possible, but a score of 600 by itself does not establish eligibility. FHA-insured mortgages are worth asking an approved lender about; their program requirements and the lender's own standards both matter. Conventional and other mortgage programs can have different requirements.
Ask the lender to assess your credit history, verifiable income, debt-to-income ratio, down payment, and closing costs together. Include taxes, homeowners insurance, mortgage insurance when applicable, and maintenance in the affordability check. The CFPB's mortgage comparison guidance explains how to compare written offers. Our 15-year vs. 30-year mortgage guide covers the payment-versus-total-cost trade-off.
Credit Cards
A secured credit card may be an option when unsecured choices are limited. It generally requires a refundable security deposit, but approval is not automatic and the deposit is not a substitute for paying the bill.
Check fees, whether the issuer reports to the major credit bureaus, and how you can eventually recover the deposit. The CFPB's credit-building guidance discusses secured cards and other tools. You do not need to carry an interest-bearing balance to build credit.
Can You Get a Loan With a 600 Credit Score?
Yes, it can be possible, but neither the score nor an advertised minimum guarantees approval. Before applying, prepare these details:
- Income and employment: how much reliable income you receive and how you can document it. Accepted income sources differ by lender.
- Existing debt payments: what you already owe each month, including obligations that may not appear in a simple budgeting estimate.
- Requested amount and term: a larger balance or a shorter term can mean a payment your income will not support.
- Credit history: recent late payments, collections, and application activity can matter beyond the headline score.
- Loan structure: whether collateral is required, and whether a co-borrower or co-signer is permitted. A co-signer takes on repayment responsibility.
- Lender requirements: eligibility can vary by product and state.
Start with an amount you need for a specific purpose, not the largest sum advertised. If the loan would only free up your credit cards to accumulate more debt, first compare a repayment plan using our avalanche vs. snowball guide.
How Much Can You Borrow With a 600 Credit Score?
There is no reliable dollar amount you can infer from a 600 score alone. Income, existing debt, collateral, loan type, interest rate, term, and lender policy determine how much may be available. A credit bureau supplies credit information; it does not decide your loan amount.
The CFPB defines debt-to-income ratio as monthly debt payments divided by gross monthly income. Different lenders and loan products have different limits. DTI also leaves out many living expenses, so passing a lender's test is not the same as having a comfortable budget.
An illustrative payment check, not an approval estimate
Suppose two applicants each earn $4,000 a month before taxes, each have a 600 score, and each are considering a $200 monthly payment.
| Illustration | Applicant A | Applicant B |
|---|---|---|
| Existing monthly debt payments | $600 | $1,400 |
| Debt payments including proposed $200 payment | $800 | $1,600 |
| Resulting DTI | 20% | 40% |
This does not predict either applicant's approval or maximum loan. It shows why identical scores do not produce identical borrowing capacity. Each person must also allow for take-home pay, rent if not included in the debt calculation, food, utilities, insurance, and savings.
To explore loan size, enter a proposed balance, an actual quoted interest rate, and a term in the loan payment calculator. Compare the payment and total interest, then account separately for fees. Do not treat the calculator result as a lender offer.
What Interest Rate Can You Expect With a 600 Credit Score?
There is no single current rate for everyone with a 600 score. Rates depend on the product, lender, market conditions, term, collateral, and the rest of your application. Lower scores can lead to higher borrowing costs, but a general range cannot tell you your actual offer.
Get written quotes for the same amount and term. The CFPB explains that APR includes interest and certain additional loan fees. Compare APR with APR, not one lender's APR with another's interest rate.
Record the APR, origination fee, net funds received, monthly payment, number of payments, and total amount repaid. Also check whether the rate can change and whether there are prepayment penalties. A low payment achieved by extending the term may cost more overall.
How to Improve a 600 Credit Score
Start with the factors on your own reports. The CFPB's guidance on building a good credit score supports these practical habits:
- Pay on time. Set reminders or automatic minimum payments if your cash flow supports them. Monitor the account so autopay does not cause an overdraft. Contact the lender promptly if you cannot pay.
- Reduce revolving balances. Lower reported card balances relative to credit limits can help utilization. There is no magic percentage that guarantees an increase, and carrying interest is unnecessary.
- Check your credit reports. Look for unfamiliar accounts, incorrect balances, and payment-history errors. Dispute inaccurate information through the appropriate bureau and company; do not dispute accurate information just to try to remove it.
- Limit unnecessary applications. Ask about soft-pull eligibility checks before applying. Avoid opening multiple accounts simply to chase a score increase.
- Evaluate older accounts before closing them. Closing a card can reduce available credit and raise utilization. Fees, fraud concerns, or difficulty controlling spending may still make closure reasonable.
- Use a realistic repayment plan. The debt payoff calculator can help you compare payment plans without opening another account.
Prioritize staying current and reducing expensive balances over paying for a promise of rapid credit repair. No legitimate plan can guarantee a specific score increase.
How Long Can It Take to Improve a 600 Credit Score?
There is no fixed timeline from 600 to 700. Lower balances or corrected errors may affect a score after updated information reaches the bureau and the score is recalculated. A history of missed payments or a thin credit file can take longer to improve.
Track the same scoring model and bureau when possible, and watch the reasons attached to your score. Progress is not always a straight line: an application, a balance change, or a reporting delay can move the number temporarily. Focus on payments and balances you can control rather than a promised deadline.
600 Credit Score FAQ
Is 600 a good credit score?
Not under FICO's general categories: 600 is fair, while good begins at 670. Other models and lenders may use different labels or thresholds.
Can I buy a car with a 600 credit score?
It may be possible. Compare the full loan cost, vehicle price, down payment, and running costs. A lender's approval does not establish that the car fits your budget.
Can I buy a house with a 600 credit score?
Possibly, depending on the mortgage program and lender. Ask about credit requirements alongside income, debts, down payment, insurance, and closing costs. Do not assume a program's minimum score guarantees a loan.
Can I get a personal loan with a 600 credit score?
Some lenders may consider you. Approval and pricing depend on the full application. Check APR, fees, repayment terms, and whether initial eligibility checks affect your credit.
How much can I borrow with a 600 credit score?
The score cannot determine the amount. Estimate an affordable payment from your budget, then compare lender offers using verified income, debt obligations, the loan term, and any collateral.
Can I get a credit card with a 600 score?
A secured card or another card may be available, subject to the issuer's requirements. Compare deposits and fees, check credit reporting, and avoid cards whose costs outweigh their usefulness.
How can I raise my score from 600 to 700?
Pay on time, reduce high card balances, correct report errors, and avoid unnecessary applications. Which steps matter most depends on your credit file; neither a 100-point gain nor a deadline can be guaranteed.
Before You Apply
Identify the model behind your score, check your reports, and choose a payment your budget can sustain. Then compare written offers rather than applying wherever approval sounds easiest. A better borrowing decision is one you can afford, not simply one a lender will approve.